
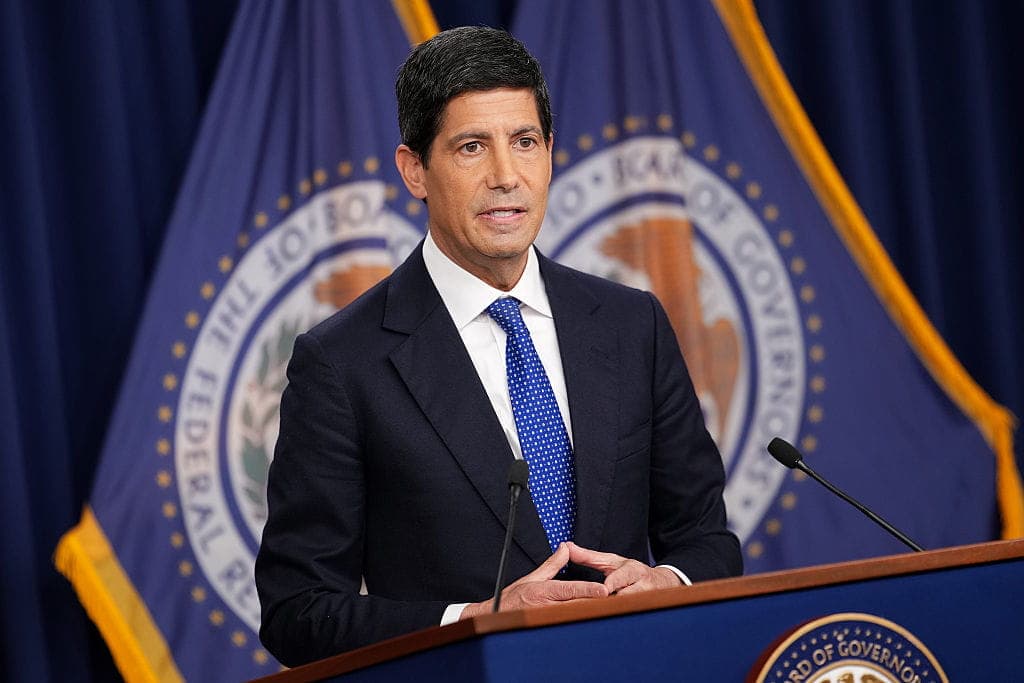
On Sept. 16, the Warshonomics agenda clashed with Trumponomics ideology. Despite President Donald Trump’s repeated demands to lower interest rates, the Federal Reserve did the exact opposite and pulled the trigger on a quarter-point hike. While central bank policymaking is a by-the-book affair that only entertains Bloomberg Terminal bros and econnoiseurs, Fed Chairman Kevin Warsh and his colleagues’ decision represented much more than a 25-basis-point hike in the benchmark federal funds rate. It could have broader political and Main Street implications.
A Hike to the Eccles Building
The Eccles Building unanimously delivered the first rate increase since July 2023. The new target range for the benchmark federal funds rate – an influential policy rate for business and consumer borrowing costs – will be 3.75% to 4%.
Free with the Daily Briefing
85EssaysUnravel the Constitution
Hamilton, Madison & Jay’s complete case for America, free and searchable in the Publius Reader.
Free with the Daily Briefing. Unsubscribe anytime.
Whether this will bring stability back to US stocks and Treasury bond yields remains to be seen. But investors could be relieved now that Kevin Warsh is walking the walk rather than just talking the talk about inflation.
At his post-meeting press conference, the new central bank chief made it clear that inflation is still too high and that the Fed will do what it takes to prevent the war-driven oil price shock from filtering through the broader economy. This, Warsh said, will cushion people most affected by a lack of price stability from the blows of high inflation.
"Our predominant focus is on the price stability side of our mandate. The plain fact is that inflation is too high, and has been for too long," Warsh told reporters. "The decision we made today was a sober decision, serious decision, responsible decision, one that we have been preparing for and thinking about in my 110 or 20 days here."
The Fed might not be one and done. According to the Summary of Economic Projections, a strong majority of policymakers (excluding Warsh) think at least one more rate hike is on the table. This makes the upcoming Consumer Price Index and Personal Consumption Expenditures inflation data even more important in the coming weeks.
Is Kevin Warsh All Warshed Up Now?
When Warsh rejoined the Federal Reserve, critics warned that he would not be an independent voice and would take his cues from President Trump. In other words, Warsh would be in rate-cutting mode and force his colleagues to adopt a similarly dovish position.
Yet the Warsh-led Fed has done none of that. A pause in June, another pause in July, and then a hike in September. This is not exactly what the president may have envisioned. Still, Trump says he backs his choice to lead the century-old institution.
“I told Kevin, I said, ‘You might as well vote with the board because it’s just not going to matter,” the president told reporters before a rally in North Carolina. “They’re doing the wrong thing. They’re a bunch of politicians. They are people put on by politicians.”
Prior to these comments, Trump took to Truth Social and reiterated that "Interest Rates in the United States should be 1%, or less, because we are the Best Credit in the World."
What makes the remarks interesting is that Trump claims he “told Kevin.” Was this a veiled shot at Warsh’s credibility? Is the chairman taking his orders from the White House? Likely not, but it is still an interesting comment for Trump to make as both sides espouse monetary independence.
Meanwhile, Warsh has often discussed the hall-of-mirrors problem facing the central bank and Wall Street. Each side depends on the other for its decisions, something he wanted to eradicate. This matters because Treasury yields had been surging across the board for weeks, partially driven by expectations that the Federal Reserve would raise interest rates. So, was this a self-fulfilling prophecy? Warsh does not think so.
“We made this decision today based on our assessment of the situation, based on our assessment of the trajectory for employment, based on our judgment on the strength of the economy, sometimes the market tries to prejudge our outcomes. I’ll observe market prices and see what they have to say. But today was our decision."
Unless it aimed to emulate the European Central Bank and take out an insurance rate hike, a chorus of market watchers says the Fed had no business being hawkish. Why?
Printing Oil at the Federal Reserve
Core inflation removes volatile energy and food prices. It is a critical measure because it examines underlying inflation, allowing the public to see whether high prices are permeating the overall economy.
In 2024, just before the presidential election, the Fed lowered interest rates when the annual core inflation rate was above 3%. In 2026, weeks before the midterms, the Fed hiked rates when the 12-month core inflation rate was 2.4%, the lowest since March 2021.
The standard playbook for a central bank is to look past a supply shock. In this case, officials would have to ignore $100 oil, $4 gas, and $6 diesel due to the war in Iran and determine how best to use their tools. Since the Fed does not drill for oil or sit on a massive crude reserve, it cannot bring down energy costs, the main driver of current inflation pressures.
Meanwhile, it is vital to remember that monetary policy operates with a lag. Even if a quarter-point hike is the solution to the world’s energy problems, it would take several months to seep through the economy.
Legendary economist Milton Friedman described this dilemma as the “fool in the shower.” When a fool notices the shower water is too cold, he cranks up the hot tap. But because the temperature takes a moment to respond, he keeps adding more heat. Before long, the water becomes scalding, forcing him to swing back and add cold water again.
Will the Fed cut interest rates if the conflict ends tomorrow and oil collapses to $70?
Warsh and Peace
Warsh has said many of the things that the top Fed critics have pontificated about for years. Trump’s pick was an inspired choice, and there is still plenty of time to prove it was the right personnel decision. For now, however, Warsh could be emulating his predecessors’ methodology and bringing nothing new to the table. Still, nobody can blame the Fed for taking proactive measures on inflation. It missed the mark in 2021, and it does not want to repeat that failure.